Buying property in Chicago calls for a close understanding of local dynamics, of condominium rules and of what makes each neighborhood distinct. This guide sets out the financial, legal and practical points so you can approach your investment decision calmly.
Get the app
What nobody tells you.
Real prices, hidden costs and the traps to check before you commit.
What you actually get when you buy an apartment in Chicago
Scroll
What you actually get when you buy an apartment in Chicago
Buying property in Chicago calls for a close understanding of local dynamics, of condominium rules and of what makes each neighborhood distinct. This guide sets out the financial, legal and practical points so you can approach your investment decision calmly.
Written by the ting.ad editorial team ·
South State Street, Chicago in Street View: drag to look around.
Beyond these financial trade-offs, your choice has to line up precisely with the rhythm of your daily life.
Buying an apartment in Chicago is not simply a matter of acquiring square meters in the Windy City. It is access to a market shaped by sharply contrasting neighborhoods, landmark architecture and unusually demanding condominium rules. You have to weigh central-city living against residential calm, while factoring in charges that are often high and that determine the real return on your investment. Understanding these fundamentals is what saves you from financial surprises at the closing table.
A sought-after architectural setting in the heart of the cityvsCondominium charges that are sometimes very heavy
The historic buildings of the Loop and Streeterville offer exceptional character and sustained rental demand. In return, the monthly condominium assessments pay for the upkeep of aging infrastructure and weigh heavily on the annual budget.
The promise of a quick resalevsSharper scrutiny depending on the condition of the building
Well-located units do sell quickly, but buyers and their advisers examine the condominium's reserve fund in fine detail. A poorly run or under-capitalised building will see its value stagnate, whatever its location.
A lively urban lifestylevsExposure to the local climate
Living in the heart of Chicago gives you immediate access to the shores of Lake Michigan and to major cultural institutions. Harsh winters, however, mean significant heating costs and call for particular attention to the insulation of older properties.
Does this place fit the way you live?
Moving from the way cities work where you come from to the American urban model also means resetting your usual reference points.
Every part of Chicago imposes its own constraints in terms of mobility, services and neighbors. A busy professional looking to be a step away from public transport will not make the same choice as an investor after the stability of a family residential district. An honest look at your usual journeys and at what you expect from local amenities should guide the choice of your future address.
The choice of the central hub
Living close to the Loop or in the Near North Side removes long daily commutes and puts you at the heart of the city's economic activity. You get an abundant cultural and dining scene within walking distance or a short transit ride. In return, urban density usually means a smaller living space for the same budget, and constant activity that can become tiring over time.
The north side residential option
Areas such as Lincoln Park or Lakeview offer an ideal compromise between urban energy and easy residential living. Tree-lined streets, the Lake Michigan beaches close at hand and local shops create an environment that favours stability. The trade-off is prices per square meter among the highest in the metropolitan area, and fierce competition whenever a good property comes up.
The bet on transitional areas
Looking at neighborhoods in the process of gentrifying gives you access to more space for a smaller initial investment. You have to accept a transitional period in which retail amenities develop gradually and where the sense of safety varies from one street to the next. This strategy demands excellent local knowledge if you are to identify the micro-areas that are moving and avoid the ones that are stalled.
Living here when you arrive from abroad: what actually changes
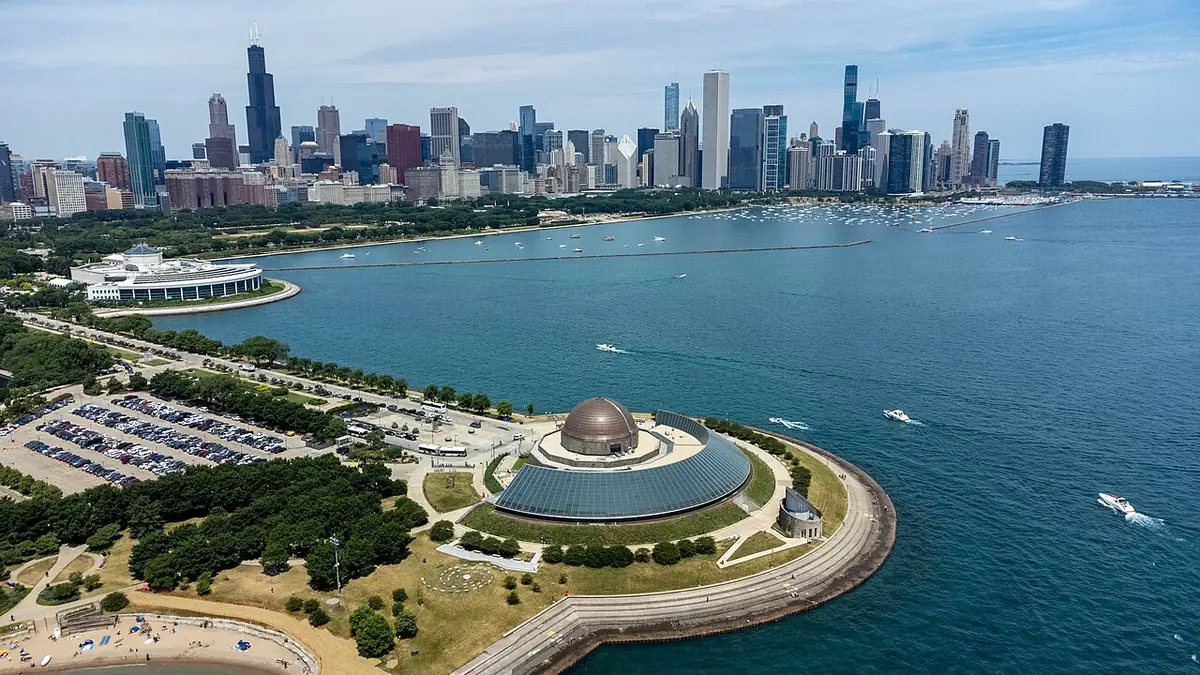
The Chicago skyline rising beyond the lakefront Adler Planetarium — Photo: Sea Cow · CC BY-SA 4.0 · Wikimedia Commons
To work out concretely where to settle, a close comparison of the different areas is the next step.
Moving to Chicago from another country changes your reference points for housing, services and property management quite profoundly. The American market runs on very different legal and contractual standards, where negotiation and transparent public records sit alongside strict condominium rules. Anticipating those divergences is essential if your move is to go smoothly.
From abroad
A single dense historic core that concentrates administration and culture
Chicago
A grid-based city, spread out and organised into specialised neighborhoods
Your daily journeys no longer revolve around one historic center: you need to master the CTA public transport network, or use a car for the outlying areas.
From abroad
The protective framework of tenancy law and regulated leases you may be used to
Chicago
Condominium bylaws that carry real authority, alongside strict local restrictions
Your building's board holds wide-ranging power over how you use your property, sometimes including bans on short-term rentals or exacting rules about interior renovation.
From abroad
An intuitive sense of how energy-efficient a building is
Chicago
A heavy reliance on shared heating systems and on air-conditioning costs
Energy bills vary considerably with the age of the building and the insulation choices made by the condominium, a budget line to audit as rigorously as the purchase price.
From abroad
The idea that age and solid masonry are what give a building its worth
Chicago
A housing stock where function comes first and where mixed steel and timber structures dominate
Judging the quality of an apartment rests less on its year of construction than on how regularly the structure has been maintained and on the overall financial health of the condominium.
Which Chicago neighborhood should you choose, and on what priorities?
Once you have a target area, budget becomes the central question in your buying strategy.
Chicago breaks down into zones with strong identities, shaped by their proximity to the lake, their industrial history or their commercial energy. Choosing a neighborhood means weighing residential quiet against cultural buzz and closeness to the main economic corridors. Each area has its own market characteristics, worth analysing before you make an offer.
The Loop & Near North Side
An intensely urban pace, set by the passing elevated trains and the activity of the financial institutions.
Suits
People working downtown and anyone who wants cultural life on the doorstep.
Trade-off
High prices per square meter and outdoor space that is often reduced to the bare minimum.
Lincoln Park & Lakeview
An elegant, green atmosphere, dominated by the closeness of the lake and the public parks.
Suits
Families and buyers looking for stable long-term value and well-regarded schools.
Trade-off
Fierce competition for good properties and particularly high property taxes.
West Loop & Wicker Park
A creative, on-trend feel, defined by former industrial warehouses converted into lofts.
Suits
Buyers after architectural originality, inventive restaurants and a lively atmosphere.
Trade-off
Price volatility that is sometimes above average and more frequent urban noise.
What does an apartment in Chicago really cost?
Chicago's expressways stay busy well into the night — Photo: AlphaBeta135 · CC BY 4.0 · Wikimedia Commons
This financial reality throws light on the exact nature of the ownership right you are about to acquire.
What it costs to buy in Chicago varies considerably with location, the type of construction and the amenities the condominium offers. Beyond the headline price shown by agencies, a buyer has to factor in local property taxes, which are often substantial, along with the monthly maintenance charges. Reading these financial components carefully is what makes your investment viable over the long term.
chicagoFor saleApartmentestimate
Median price / m²US$3,420Half the apartments sell below this
Median priceUS$320kthe average is 14% higher — a few very large properties pull it up
Most common2 bedrooms40 % of listings
Average size89 m²
By number of bedrooms
Bedrooms
Share of market
Avg price
Price / m²
Avg size
1
34 %
US$242k
US$4,032 +12 %
60 m²
2most common
40 %
US$324k
US$3,600
90 m²
3
21 %
US$428k
US$3,420best value / m²
125 m²
4
5 %
US$612k
US$3,600
170 m²
Each row is an average, compared against the area average of US$3,600 / m². These are indicative estimates of a typical local market, not a measured sample of live listings. Check current listings before relying on them.
What you can actually own: condominium versus outright ownership
Securing your purchase then depends on following the local legal steps closely.
The American property market draws a clear line between collective forms of ownership and independent properties. In Chicago, the great majority of apartments are bought under the condominium regime. That legal status carries specific rights and duties which set firm limits on what you are free to change and which require active participation in the collective management of the building.
The condominium regime
You own your apartment outright, together with a share of the building's common areas. The board manages structural upkeep and shared services through compulsory monthly assessments and through special assessments when major work is needed.
What it changesYou need to read the minutes of past owners' meetings very closely, to identify any work that is coming and to avoid carrying unforeseen charges from the day you move in.
The single-family home or townhome
You own the building and the land it sits on outright, with no condominium association to govern your maintenance or exterior renovation decisions. The financial and practical burden of upkeep rests entirely on your shoulders.
What it changesYou keep complete freedom of action but carry the full cost of the roof, the facade and the heating systems directly, with no way to share it with other owners.
The rule to understand before you pay a deposit
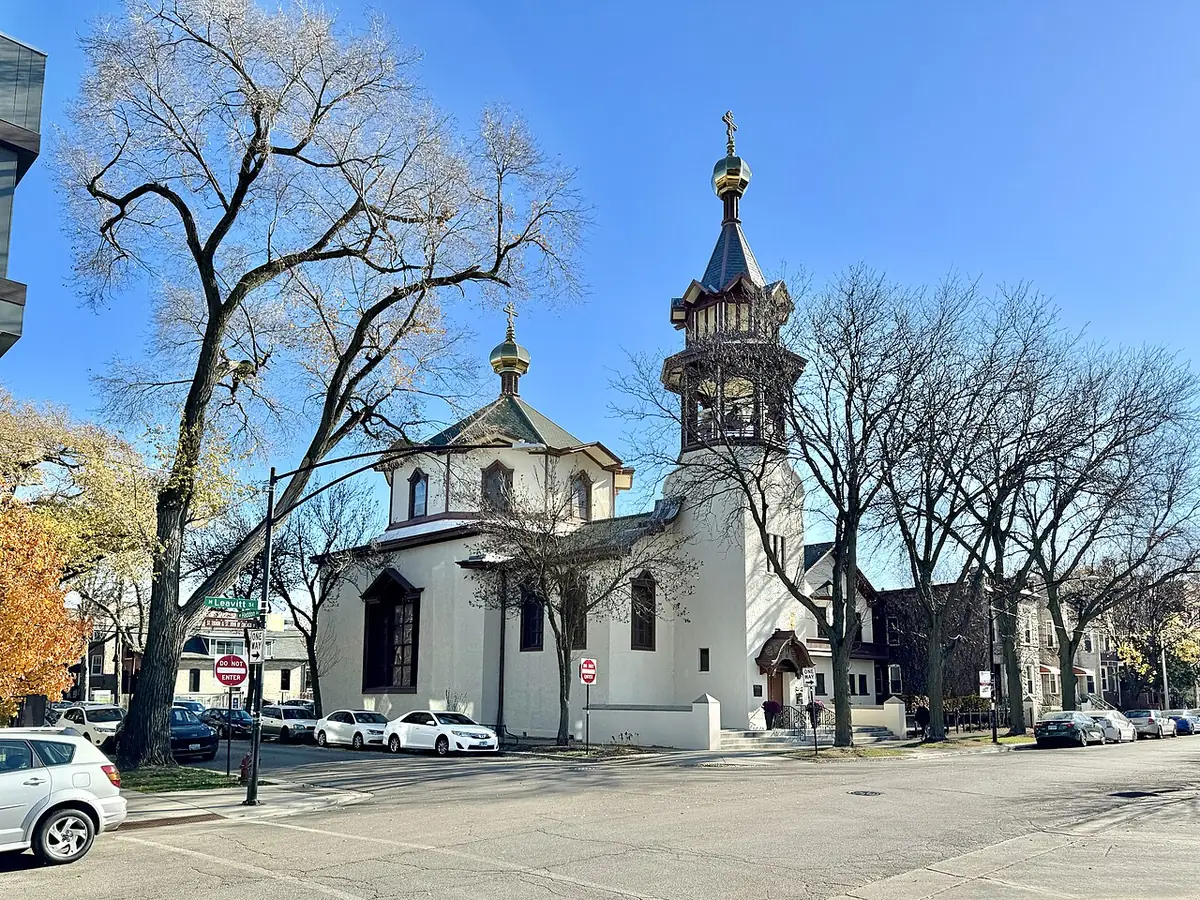
A landmark corner in Chicago's Ukrainian Village neighbourhood — Photo: w_lemay · CC BY-SA 2.0 · Wikimedia Commons
To handle all of these steps calmly, it helps to follow a methodical timeline.
The property transaction system in Illinois places great weight on the preliminary document review, carried out under the supervision of specialist attorneys. Paying a deposit without auditing the condominium's accounts and examining any easements on the property exposes you to major financial risk. Understanding this chain of safeguards is what protects your interests as a buyer effectively.
Making the initial offer to purchase and placing earnest money in a dedicated escrow account.
A thorough review of the condominium documents by your attorney, including the financial statements and any ongoing litigation.
An independent technical inspection to detect hidden defects and assess the condition of the installations.
Lifting or renegotiating the contingencies within the deadline set out in the contract.
Preparing the final transfer deed and the release of funds by your lender.
The final signing and the handover of the keys to your new Chicago apartment.
How a property transaction unfolds, step by step
In short, a successful purchase in Chicago rests on careful preparation and on anticipating its local particularities rigorously.
Carrying a Chicago property project through means coordinating several professionals: real estate agent, attorney, inspector and mortgage broker. Each of them plays a precise role in making the transaction legally and financially secure. Following this sequence scrupulously is what keeps your purchase moving smoothly.
YouConfirming up front what you can financeGet a pre-approval letter from a lender before you even start viewing, so that your offers carry weight with sellers.
Your agentTargeted selection of properties and visits to the neighborhoodsView several properties, comparing the condominium charges and the real state of upkeep of the buildings you shortlist.
Your attorneyDrafting and negotiating the offer to purchaseInclude contingencies that protect your deposit if serious defects come to light in the condominium.
The inspectorA full technical audit of the homeCheck the state of the plumbing, the electrics, the roof and the heating system so you can anticipate future work.
The title companyVerification of title and of any charges on the propertyMake sure there are no hidden liens or mortgages encumbering the property before the final transfer of funds.
All partiesFinal signing and closingSign the deed of sale, wire the remaining funds and have your ownership publicly recorded.
Condominium apartment or single-family home in Chicago: weighing collective management against private space
Once the type of property is settled, the central question becomes the overall financial balance of your move.
Choosing between a condominium apartment and a single-family home in Chicago shapes your daily life, your budget and your future flexibility. Condominiums, very common in dense neighborhoods such as the Loop, River North or Lincoln Park, come with built-in amenities: a concierge service, a landscaped roof terrace, a gym and exterior upkeep entirely delegated to the homeowners association. That formula suits buyers who want urban convenience, a short trip to the business district and freedom from chores such as clearing winter snow or replacing the roof. In return, monthly condominium charges can be high and can rise from one year to the next, while the major decisions about the building rest with a board on which your voice does not always carry much weight.
Opting for a single-family home instead, more readily found in residential neighborhoods such as Edgewater, Beverly or parts of West Ridge, gives you complete autonomy and private living space with no immediate neighbor above you. You manage the property on your own terms, with no compulsory monthly payment to a third party, which leaves more budgetary room for renovation or extension work. That independence has a direct and invisible cost, however: maintaining the structure falls entirely to you. In Chicago, harsh winters test foundations, pipework and roofs severely, turning every snowstorm or cold snap into a potential financial worry. You also have to accept commutes that are often longer to reach the downtown employment areas.
The Chicago market sharpens this structural divergence through price dynamics and resale liquidity. Condominium apartments generally offer a more accessible entry point into the sought-after neighborhoods near Lake Michigan, but their long-term appreciation can be held back by plentiful supply and by charges that future buyers sometimes find off-putting. Single-family homes, rarer within the city limits, are under permanent pressure that supports their value, even though the initial investment required is markedly higher. Your final decision should therefore rest on a clear-eyed reading of your tolerance for maintenance risk, your current way of life and how long you expect to hold this asset in the Illinois metropolis.
Finally, examine the financial health of the condominium carefully before signing any offer on an apartment, because an insufficient reserve fund or unfunded facade work will inevitably translate into special assessments. For a house, always plan a rigorous inspection to establish the condition of the boiler, the drainage and the thermal insulation against the local climate. By weighing these concrete constraints from the outset, you will avoid financial disappointment and choose the type of property that fits your life in Chicago, rather than giving in to a fleeting infatuation.
What overall budget do you need to secure to live long term in a Chicago apartment?
Beyond the purely financial side, it is the daily rhythm and practical organisation that will test your choice.
Buying an apartment in Chicago is not summed up by the headline price on the listing. You have to factor in a range of recurring and exceptional expenses that make up the real cost of ownership. Historical local market data show that condominium charges, the very particular property tax system in Illinois and insurance costs weigh heavily on an owner's annual budget. Anticipating these lines rigorously is what keeps you out of a financial dead end in the first years of ownership.
Monthly and annual cost lines for an apartment in Chicago
Cost line
Estimated amount (range)
Frequency
What makes it vary
Condominium charges (HOA)
$350 to $900
Monthly
Floor area, building services (doorman, elevator, gym)
Property tax
1.5% to 2.5% of value
Annual
Exact location (Cook County), municipal assessment
Home insurance (HO-6)
$400 to $900
Annual
Personal property cover, deductible, floor the apartment is on
Interior maintenance and repairs
$1,000 to $3,000
Annual
Age and condition of the apartment, appliances included
The amounts shown are for a standard two-bedroom apartment in Chicago's central or intermediate neighborhoods and vary with the year the building was constructed.
Upfront acquisition costs to plan for
Type of cost
Average estimate
How it is paid
Closing costs
2% to 4% of the purchase price
In cash on the day of final signing
Transfer taxes and local duties
Varies by municipality
Included in the closing costs
Home inspection
$400 to $700
Paid directly to the inspector you appoint
These costs come on top of the down payment lenders require in order to grant a mortgage in Cook County.
Transport, services and daily life: what does an ordinary Tuesday look like for a Chicago resident?
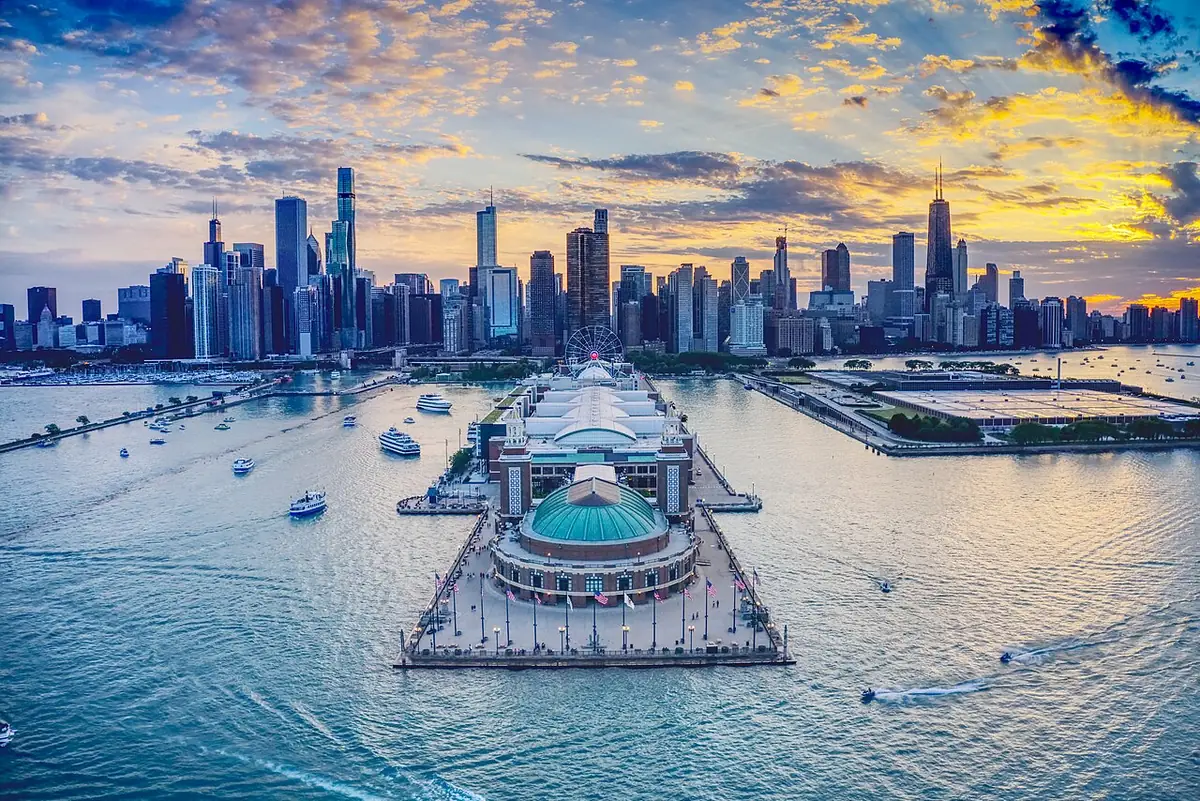
Navy Pier, a lakefront gathering spot minutes from downtown — Photo: Moses8910 · CC BY-SA 4.0 · Wikimedia Commons
But what is visible at first glance often hides technical realities that sellers leave unmentioned.
To judge whether buying in Chicago makes sense, nothing replaces walking through an ordinary weekday hour by hour. Between commuting on the CTA (Chicago Transit Authority) network, handling local errands and adapting to changeable weather, every neighborhood sets its own tempo. That kind of immersion lets you measure the real effect of your future address on your own balance, well beyond the promises in agency advertising.
07:30CTA station (Brown Line or Blue Line)The start of the morning trip toward the financial district in the Loop. How reliably transit runs is a key indicator of your apartment's locational value.
09:00Workspace or office downtownArriving at the office after a smooth trip if you live along the main lines, or one broken up by several changes if your home is further out.
12:30Local shops and grocery storeA lunchtime break given over to picking up essentials. Having supermarkets with fresh produce less than ten minutes away on foot simplifies household logistics considerably.
17:30Heading home, with a stop at the pharmacyHandling everyday errands on the way back. Being able to reach basic health services on foot avoids wasting time at the end of the day.
19:00Winding down in the neighborhood park or by the lakeUsing the public green spaces, essential in a dense city. Quality of life in Chicago depends largely on having a park or a lakefront path close at hand.
What the listing will never tell you about the technical reality of Chicago buildings
Those deliberate omissions open the way to common regrets that only become clear after several months in the place.
The sales copy published on property portals highlights the light, the renovated kitchen and the closeness of transit, while deliberately passing over the structural constraints inherent in Chicago's housing stock. Understanding these blind spots protects you from risky investments and gives you the arguments you need to negotiate the price with your eyes open.
The real condition of the risers and the shared plumbing
Many older buildings put up in the early twentieth century still have their original lead or corroded cast iron pipework. Replacing it across the whole condominium means enormous work and exceptional demands on your personal cash.
Litigation under way within the building's board
A condominium that is badly run or locked in a slow legal fight with contractors cannot make decisions about the upkeep of the common areas. That translates into a rapid loss of value for your apartment and a resale that becomes extremely difficult.
The real noise impact of traffic and rail lines
A viewing on a sunny Sunday morning tells you nothing about the deafening racket of CTA elevated trains or of major roads during weekday rush hours. Poor sound insulation in mid-range construction erodes quality of life quickly.
How property taxes are assessed and revised
The Cook County assessment system is complex and prone to sharp increases every three years during the reassessment cycle. An apartment whose tax bill looked moderate in the year of purchase can see its local taxes suddenly double, with no simple recourse.
Post-purchase disillusion: what new owners regret after six months in Chicago
Faced with these demands, some buyer profiles would do better to postpone their purchase or to change strategy entirely.
Looked likeA charming tree-lined street with easy parking outside the building for when friends come over
Turned outA total parking ban during winter snow alerts and frequent towing, turning every trip back from the shops into an obstacle course
Would have caught itAlways check whether the apartment includes a deeded parking space, or study the real supply of covered parking within a two hundred meter radius.
Looked likeAn economical shared heating system included in the monthly condominium charges
Turned outAn old radiator impossible to control individually, producing unbearable heat in winter or persistent cold depending on the floor and the orientation of the apartment
Would have caught itAsk for a detailed report on how the building is heated and review the energy bills for the past twelve months before submitting a firm offer.
Looked likeA fashionable, fast-rising neighborhood with busy cafes and vibrant nightlife at the end of the street
Turned outConstant night-time noise, recurring antisocial behaviour and no chance at all of sleeping with the windows open from Thursday to Saturday night
Would have caught itMake scouting visits at night, on weekdays and at the weekend, to judge objectively how noisy the immediate surroundings are and how busy they get.
Looked likeA safe rental or capital investment thanks to strong historic demand in the Chicago market
Turned outDrastic restrictions imposed by the condominium rules, banning short-term letting outright and limiting long-term letting
Would have caught itRead the condominium documents in full (the Condo Bylaws and the Rules & Regulations) to identify restrictive clauses on subletting or on pets.
At-risk profiles: who should absolutely not buy an apartment in Chicago right now?
It is time to draw these elements together and make an informed, clear-headed decision, free of any haste.
Buying is not the right answer for every life path. In Chicago, the tax burden, the rigidity of the credit market and the harsh weather make ownership a financial trap for certain buyers who are in a hurry or poorly prepared. Identifying these situations helps you avoid capital allocation mistakes with heavy consequences.
The young professional whose job mobility is uncertain in the short term
→Committing to a purchase in the first year after arriving in the Chicago area
Closing costs on the way in and sales commissions on the way out absorb any potential gain over a period shorter than five years, turning a quick resale into a net financial loss.
The investor with no patience for administration and owners' meetings
→Buying a condominium apartment without analysing the financial soundness of the association
Running a building collectively in Chicago demands close attention to the forecast budgets and active participation in decisions, in order to absorb the failures of owners who do not pay.
The household with only a bare minimum of emergency savings
→Committing all of its cash to the down payment and the closing costs
With no financial cushion in the event of a major equipment failure or an unforeseen special assessment, you move straight into mortgage default.
Summary and final decision: are you genuinely ready to buy in Chicago?
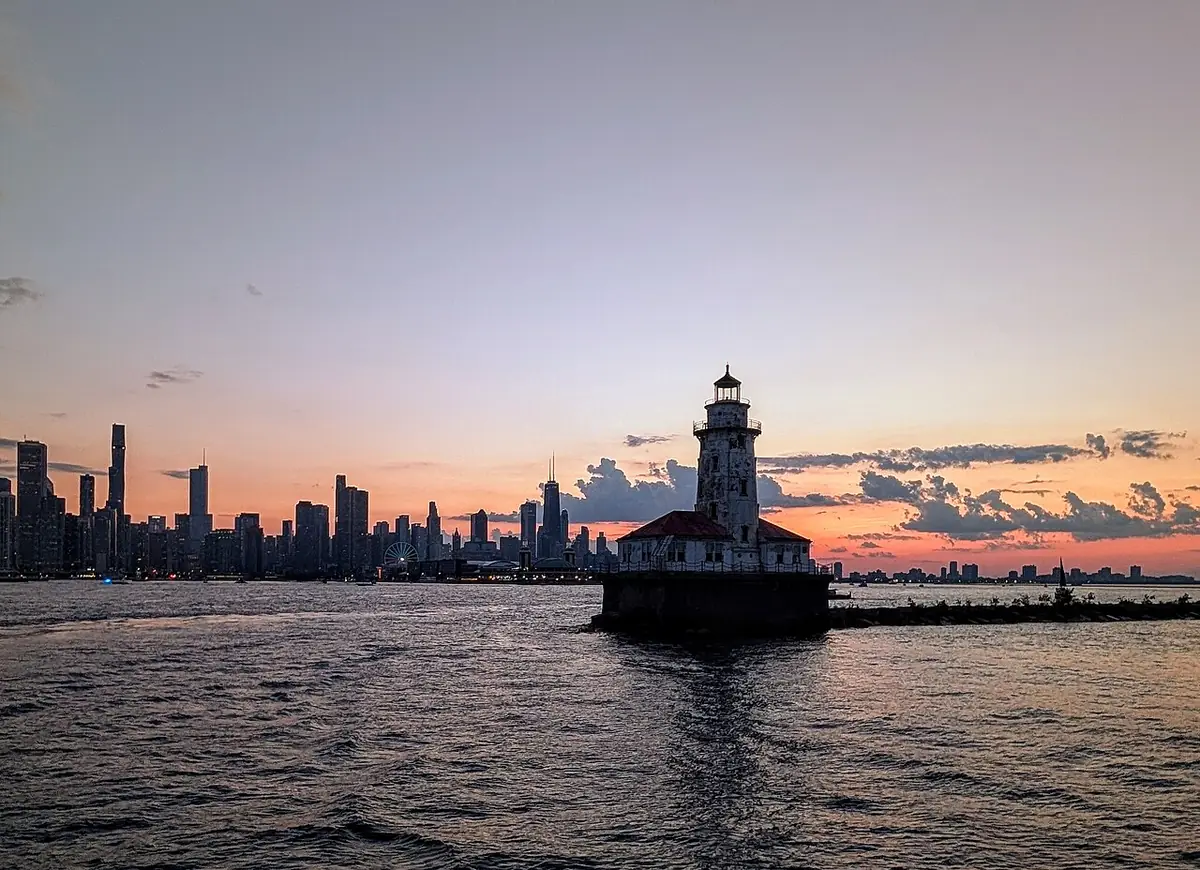
A quiet close to the day at the Chicago Harbor Lighthouse — Photo: Dicklyon · CC BY-SA 4.0 · Wikimedia Commons
At the end of this analysis, you have a realistic view of the constraints, the hidden costs and the daily realities that define the residential property market in Chicago. Buying an apartment in the Illinois metropolis is not a matter of aesthetic impulse but a long-term commitment that demands solid finances and a genuine fit with the way you live. If your professional horizon is stable for the next five to seven years, if you have taken in all the recurring charges tied to local taxation and if you can tolerate the severity of the winter climate, buying a well-located property is a structurally sound and durable decision.
If, on the other hand, your future plans remain uncertain, if your available savings would not survive an unforeseen special assessment, or if you dread the upkeep demands of an older building, renting is a far more protective alternative for your capital. The Chicago market will keep offering opportunities to methodical buyers who take the time to work through the technical and financial documents on the properties they consider. Never let yourself be rushed by the sales arguments of intermediaries, and always insist on written guarantees before you commit legally.
Take the time to visit several neighborhoods at different hours, talk to residents already living in the buildings you are considering, and have any potential work costed precisely by independent professionals before making an offer. Your future peace of mind in Chicago depends directly on how rigorous that preparatory stage is. If every criterion supports your plan, you can approach this decisive step with confidence, knowing exactly what you are buying, what it costs you and what it means for your daily life.
Related questions
What are the average closing costs when buying an apartment in Chicago?
Closing and transaction costs in Cook County generally represent between 2% and 4% of the total purchase price. They cover the fees of the real estate attorneys, local transfer taxes, the cost of the technical inspection and the expense of putting together your mortgage file with your lender.
How does property tax work for real estate in Chicago?
Property tax is calculated on the official valuation carried out by the Cook County Assessor's Office. The effective rate generally runs between 1.5% and 2.5% of the market value of the property, depending on the precise location and on the tax classification assigned to the building during the triennial cycle.
Do you have to hire an attorney to buy an apartment in Chicago?
In the State of Illinois, using a real estate attorney is a deeply established and almost universal practice, both to secure the drafting and negotiation of the initial Purchase Agreement and to oversee the closing of the sale.
Which Chicago neighborhoods are best for a first purchase?
The choice of neighborhood depends on your priorities in terms of transport, budget and lifestyle. Intermediate areas such as Lincoln Square, Andersonville, Lakeview or parts of West Loop offer a good compromise between cultural energy, access to the CTA network and long-term value.
What is a condominium reserve fund (HOA reserve fund) in Chicago?
The reserve fund is collective savings built up by the condominium out of the monthly charges paid by all the owners. It is meant to pay for major future maintenance on the building, such as facade restoration, roof replacement or new elevators, and so to avoid sudden and painful special assessments.
How does a home inspection work before a purchase?
The inspection is carried out by a certified independent professional who examines the structural condition of the apartment or house, including the plumbing, the electrical installation, the heating system, the ventilation and the roof. The written report allows the buyer to negotiate a price reduction or to require repairs before the contingencies are lifted.
What are the common restrictions on short-term rentals in Chicago?
The City of Chicago applies strict regulation to Airbnb-style rentals, and many condominium rulebooks flatly prohibit any rental shorter than thirty days, or set firm quotas in order to preserve the quiet of permanent residents.
What effect does the Chicago winter have on maintaining a property?
Harsh winter conditions subject buildings to repeated freeze and thaw cycles that accelerate wear on masonry joints, foundations and exterior pipework. A careful check of the thermal insulation and the heating system is essential if you want to avoid excessive energy bills.
What is a deeded parking space in Chicago?
It is a parking spot whose ownership rights are legally attached to your condominium unit, or held separately under its own title. In dense neighborhoods, having a deeded space significantly protects the resale value of your apartment.
How long does it take between accepting an offer and getting the keys in Chicago?
The average time to complete a property transaction in the Chicago area generally runs between thirty and forty-five days. That period is needed to finalise the mortgage, carry out the technical inspection and complete the legal checks by the respective attorneys.
Property review of ting
No ting properties in Chicago yet
Be the first — share it on ting and it shows up right here.