Buying a house in London is a major financial commitment, and it calls for a firm grip on the subtleties of a complex, heavily regulated market. This guide sets out the essential mechanics, the district choices and the legal stages you need in order to move forward with confidence.
Get the app
What nobody tells you.
Real prices, hidden costs and the traps to check before you commit.
Why the London property market has to be read beyond appearances
Scroll
Why the London property market has to be read beyond appearances
Buying a house in London is a major financial commitment, and it calls for a firm grip on the subtleties of a complex, heavily regulated market. This guide sets out the essential mechanics, the district choices and the legal stages you need in order to move forward with confidence.
Written by the ting.ad editorial team ·
East Street, London in Street View: drag to look around.
That tension between character and technical constraint plays out very concretely, depending on your own situation.
Buying a house in the UK capital is not simply a matter of acquiring square metres or enjoying a central location. Behind the Georgian or Victorian facade sits a complex set of ownership constraints, historic easements and maintenance obligations that redefine the real value of the property across the decades. Understanding that gap between the aesthetic promise and the operational reality is the first essential step for any clear-eyed buyer.
The visible promise of timeless architectural charactervsThe demanding reality of conservation rules
Owning a Victorian or Edwardian house in London carries undeniable prestige and a much sought-after look. In return, the restrictions local authorities place on external alterations rule out any improvisation when it comes to energy retrofits or extensions.
The appeal of a central, superbly connected locationvsUrban density, persistent noise and chronically scarce parking
Settling in the liveliest areas guarantees immediate access to services and to the strongest employment centres. It does, however, mean accepting constant exposure to noise, tightly controlled road traffic and extremely high parking costs.
Property seen as a universal safe haven for capitalvsExposure to UK interest rate swings and to specific taxes
London bricks and mortar may have a reputation for long-term financial solidity, but holding the asset means variable local taxes and high structural maintenance costs, which weigh directly on the net return for an owner-occupier.
The prospect of private outdoor space with a garden in a megacityvsHow small those outdoor spaces often are, and how overlooked
Finding a house with a garden in London is a rare privilege, but these urban plots often turn out to be cramped, shaded by the buildings next door and directly overlooked by neighbours, because of how densely the city is built.
Which kind of buyer are you, faced with what makes this city particular?
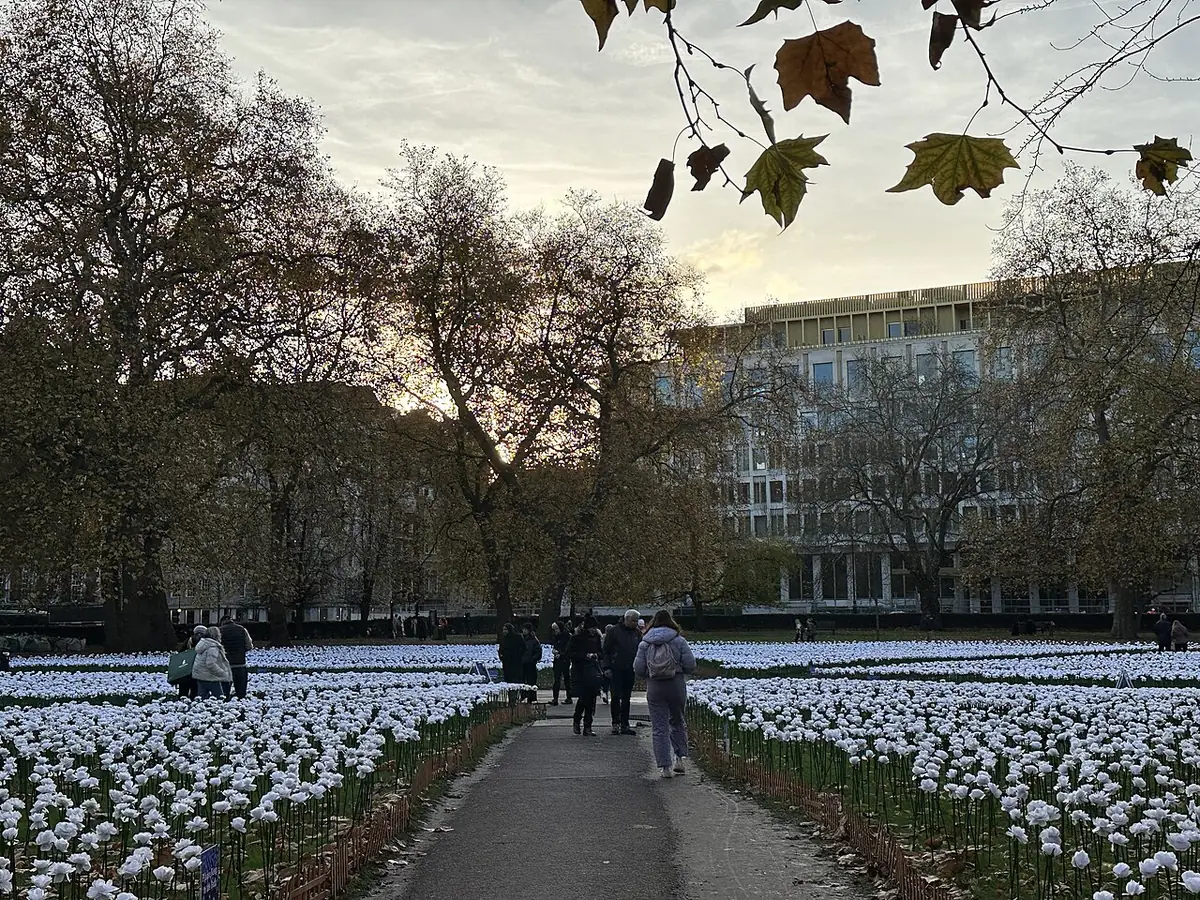
Green squares offer a quiet break from city life — Photo: Matt Brown · CC BY 2.0 · Wikimedia Commons
That personal positioning takes on a particular colour when you arrive with reference points built somewhere else entirely.
Buying a house in London answers to different priorities depending on whether you intend to settle permanently with a family, to spend a few months a year here, or to secure a long-term capital investment. Each buyer profile has to work through precise trade-offs on distance from the centre, living space, and tolerance for energy improvement works.
Looking for family roots and residential stability
Families generally favour residential areas in Zone 3 or Zone 4, where they can find mid-sized houses with a garden and be right next to the best state or private schools. That choice means accepting a longer daily commute into the business districts, and giving up immediate evening buzz in favour of quiet, leafy neighbourhoods.
The trade-off between being central and having space
Professionals who want to be right next to the City or Westminster often have to give up the traditional single-family house with a private garden in favour of something more compact. If you do decide on a house in a close-in area, you will have to accept a markedly higher budget for living space that is often more modest than what the outer areas offer.
Building an asset that lasts and can be passed on
For buyers focused on long-term value rather than the daily constraint of a commute, the emphasis falls on the intrinsic quality of the building and the history of the neighbourhood. These buyers look for properties with character that need little structural change, and they accept managing from a distance along with the costs that come with maintaining an older property.
What genuinely surprises buyers arriving from another country
Beyond the legal side, the district you settle on dictates most of your day-to-day London life.
The UK property system runs on legal, customary and architectural rules that are radically different from those most incoming buyers are used to. Failing to anticipate these structural differences leaves an unprepared buyer open to serious misunderstandings during the negotiation, the survey and the everyday running of a new London property.
From abroad
In many countries, a sale is locked down by a binding preliminary contract as soon as the parties agree on the property and the price, with strict cooling-off periods.
London
In London, the pre-contract phase is long and non-binding ('subject to contract') right up to the formal exchange of contracts.
Throughout that period, which can run for several weeks, either party can walk away or change their terms with no immediate financial penalty, so you need to move quickly and have seasoned legal support behind you.
From abroad
In many countries, land ownership is almost always outright and absolute.
London
In London, many houses, particularly Victorian ones or those on estates, can fall under leasehold or carry a ground rent.
You must check meticulously how many years are left on the lease and what charges go with it, because a short lease can badly depress the value of the property and make mortgage financing complicated.
From abroad
In many countries, the compulsory technical reports are gathered into a single pack the seller provides before the preliminary contract.
London
In London, the rule of 'caveat emptor' (the buyer alone is responsible) applies, and it is up to you to commission and pay for your own thorough surveys.
Instructing an independent chartered surveyor to carry out a full home survey is essential if you want to identify hidden defects, structural damp, or worn-out services that the seller will not volunteer.
From abroad
In many countries, local taxation rests on property and residence taxes scaled by floor area and household income.
London
In London, council tax applies, with bands set by the property's estimated value in 1991.
The annual amount varies sharply from one borough to another, and it absolutely has to be built into your calculation of recurring running costs.
How to find your way among London's residential districts
These local dynamics translate into a financial reality worth looking at without any ambiguity.
London's geography is an archipelago of villages with sharply contrasting identities, moods and budgets. Choosing a house in the capital is not just a calculation of distance from the centre: it is a fine match between the rhythm of your life, the local social mix, the quality of the green space and how accessible public transport is.
North London (Highgate, Islington, Muswell Hill)
A well-heeled village atmosphere, with green hills, well-known parks and streets lined with superb Georgian houses.
Suits
Families and buyers looking for a harmonious compromise between rich cultural life, open green space and an excellent reputation for schools.
Trade-off
Prices per square metre among the highest in the city, and fierce competition for the few family houses that come up for sale.
South London (Dulwich, Clapham, Wandsworth)
A lively residential setting, strongly focused on neighbourhood life, with large open spaces and a high proportion of Victorian houses.
Suits
Those who want more living space, a sociable atmosphere and direct access to large parks without straying too far from the Thames.
Trade-off
Journey times to the business districts north or east of the City can stretch out, because the rail links are less direct.
West London (Chiswick, Ealing, Richmond)
An elegant mix of historic architecture, riverside settings and first-rate transport links running straight out to the west.
Suits
Buyers who value residential calm, the waterside, the big royal parks and quick access to the main roads out of town.
Trade-off
A very high price level overall, and strong international demand pressing on the whole area.
East London (Hackney, Walthamstow, Greenwich)
Creative, contemporary energy, marked by the revival of former industrial districts, busy markets and an alternative cultural scene.
Suits
Young professionals, creatives and investors looking for momentum, regeneration projects and the prospect of rising values.
Trade-off
Differences that are still pronounced from one street to the next in safety, cleanliness and the quality of local public services.
What the budget reality and the price ranges look like in London
Beyond the headline purchase figure, the legal nature of the ownership is a fundamental trade-off in itself.
The London property market is characterised by heavily stratified prices, depending on the area, the type of property and the state it is in. Since nobody can predict exactly where rates will go or fix a universal price, looking at observed ranges is what lets you calibrate your plans realistically and avoid disappointment at the first viewings.
londonFor saleHouseestimate
Median price / m²£6,232Half the apartments sell below this
Median price£781kthe average is 14% higher — a few very large properties pull it up
Most common2 bedrooms63 % of listings
Average size119 m²
By number of bedrooms
Bedrooms
Share of market
Avg price
Price / m²
Avg size
2most common
63 %
£796k
£6,691
119 m²
3
28 %
£971k
£6,166 −6 %
158 m²
4
9 %
£1.18m
£6,035best value / m²
196 m²
Each row is an average, compared against the area average of £6,560 / m². These are indicative estimates of a typical local market, not a measured sample of live listings. Check current listings before relying on them.
The fundamental legal trade-off: freehold versus leasehold
Once those legal foundations are absorbed, the chronological run of a transaction demands attention at every moment.
Property ownership in the UK rests on an essential legal distinction that determines how freely you can manage the asset and what it will be worth in the long run. Understanding the line between absolute ownership and time-limited ownership is essential for any overseas buyer unfamiliar with British practice.
Freehold (outright ownership)
Buying freehold means you own both the structure of the house and the land it is built on, with no limit in time. It is the most sought-after standard for detached and terraced houses, because it gives you complete autonomy over works, maintenance and passing the property on to your family.
What it changesYou decide about your roof, your facades and your interior alterations, subject only to local planning rules, with no third-party landowner to answer to and no periodic charge to pay.
Leasehold (a long lease)
Buying leasehold means you are buying the right to occupy the house for a period set by the original lease (often 99, 125 or 999 years), while another party (the freeholder, who owns the land) keeps ownership of the ground. This arrangement is more common for flats, but it also applies to some houses in shared blocks or integrated developments.
What it changesYou have to pay an annual ground rent as well as service charges for the common parts, and you need to watch the remaining lease term closely, because once it falls below 80 years the cost of extending rises exponentially.
The critical timeline of a London property purchase
To get through that marked-out route, it helps to picture who is involved at each point in the process.
The British buying process follows a strict sequence in which each stage commits the parties in specific legal ways. Anticipating that chain of consequences is what lets you avoid administrative deadlocks and protect your investment against the hazards of the negotiation.
The decision to buy starts with an active search and with obtaining a lender's decision in principle.
A thorough viewing of the property, and an offer put to the seller through the estate agent.
Formal acceptance of the offer, and the necessary appointment of a solicitor or conveyancer to represent your legal interests.
Independent surveys, and the exhaustive property searches carried out by your legal adviser.
Exchange of contracts, the moment the deal becomes legally binding, with a deposit generally set at ten per cent.
Completion of the transaction, with payment of the balance of the price, the effective transfer of ownership and the handover of the keys.
Who is involved, and when, in buying your house
A successful London transaction rests on the rigorous coordination of several specialists whose roles are strictly bounded by British legal custom. Knowing what each of them can and cannot do helps you keep the conversation efficient and the file moving.
The estate agentThe commercial intermediary in the saleThe agent acts for the seller, organises viewings, collects offers and makes the initial link between the parties. The agent has no legal standing to draft the terms of the contract.
The solicitor or conveyancerThe buyer's legal adviserThey check that title is valid, carry out the searches with the borough, draft the legal documents and secure the transfer of funds through to completion.
The chartered surveyorThe analyst of the building's conditionThey carry out a meticulous physical inspection of the structure, the foundations, the roof and the services, to identify any hidden defects or essential remedial works.
The mortgage brokerThe financing specialistThey review your financial profile, compare offers from different British or international lenders and negotiate the loan terms best suited to your circumstances.
HM Land RegistryThe land registration authorityIt formally records the transfer of ownership once the transaction has completed, which is what makes your right over the land and the building good against the world.
House or flat in London: weighing space against shared ownership
Once that structural choice is settled, the central question of overall financing and the real budget arrives immediately.
Choosing between a Victorian or Edwardian house with its patch of ground and a modern flat in a managed building immediately raises the question of your relationship with free time and independence. In London, single-family houses sit mostly in the outer residential areas, in boroughs such as Ealing or Bromley, while flats concentrate the supply in the central districts and around transport hubs. That initial geographical split redefines not only your daily commute but also your exposure to the hidden costs tied to the fabric of the building itself.
Going for a house means shouldering full responsibility for the roof, the foundations and the insulation, with no way of sharing those bills with neighbours. Owners of older houses face energy bills that are often high, because of uninsulated solid walls and strict rules on preserving local architectural character. Even so, the absence of shared charges, the famous ground rents and service charges that keep climbing in the capital, brings a welcome degree of financial autonomy over the long run, for anyone willing to do the work or to supervise tradespeople.
A London flat, whether it is in a Victorian conversion or a contemporary tower along the Thames, makes day-to-day logistics simpler, thanks to concierge services and the shared upkeep of the common parts. In return, you become dependent on the decisions of a managing agent or a residents' association, with freehold and leasehold governing the British market with formidable legal complexity. Annual charges can double without warning if major works to the facade or an upgrade to the lift are voted through by the majority.
The trade-off, then, comes down to private outdoor space against the relative predictability of shared maintenance. Families with young children often prefer houses, for the acoustic peace and the private green space, while single people and couples without children opt for the centrality and security of a managed block. Your decision should be rooted in your tolerance for administrative constraints on one hand and physical maintenance costs on the other, well before you look at floor area alone.
What total budget to plan for buying and living in a property in London
Terraced houses and corner shops along a typical London street — Photo: Lewis Clarke · CC BY-SA 2.0 · Wikimedia Commons
Once the budget is settled, it is worth looking at how an ordinary day actually runs, to gauge the weight of the commute.
Buying a house in London is not limited to the price shown on the property portals or to the size of your initial mortgage. From the outset you have to build in the specific local taxes, such as Stamp Duty Land Tax, whose progressive bands add considerably to the cash you need up front. On top of that, the local transaction costs, structured differently from those elsewhere in Europe, include substantial solicitors' fees and search fees. Finally, the everyday cost of living and the council tax collected by each borough weigh heavily on how much a household can save each month.
Upfront costs and purchase taxes
Cost item
Estimated amount or range
Effect on the financing plan
Stamp Duty Land Tax (SDLT)
From 0% to 12% depending on band and status
A progressive tax paid at completion, through your solicitor.
Conveyancing fees
Between GBP 1,500 and GBP 3,500
Compulsory legal costs to secure the transfer of ownership and carry out the searches.
Home survey report
Between GBP 600 and GBP 1,500
Essential for identifying hidden defects, damp and the state of the roof before you commit.
First-time buyers get specific relief on stamp duty for properties below a regulatory threshold that is updated periodically.
Recurring charges and annual maintenance costs
Type of charge
Average annual cost
Movement and variability
Council tax
Between GBP 1,200 and GBP 3,000 a year
Varies sharply with the borough you live in and the property's valuation band.
Home insurance (buildings and contents)
Between GBP 400 and GBP 900 a year
Covers water damage, fire and theft, and is required by mortgage lenders.
Reserve fund for works
1% to 1.5% of the value of the property
The amount it is sensible to set aside each year to cope with the natural ageing of the house.
Energy bills (gas and electricity) come on top of these items and depend enormously on the EPC rating of the house.
What an ordinary Tuesday actually looks like living in a house in London
Beyond that apparent routine, a great deal that matters never shows up on a normal viewing.
Living in a house in London calls for careful logistical organisation to reconcile the commute with neighbourhood life. The morning alarm is often dictated by the timetable of public transport, or by how freely the outer road traffic is moving if you depend on a car. Getting children into local schools means starting the applications well before you finally move in. Every district has its own ecosystem, and it shapes your shopping habits and your social contacts across the week.
07:30Residential street, setting offGetting ready in the quiet of the house, and a quick check on transport or on local traffic.
08:15National Rail or Underground stationThe commute into the business districts, a good moment to take the measure of London's flow of commuters.
12:30Local shops and the lunch breakQuick shopping with the independent traders in the neighbourhood, or at a convenience store, over the midday break.
17:45Home again, and the household adminArriving back, dealing with any small routine maintenance issues and opening the official post.
19:30Neighbourhood life and health servicesPerhaps an appointment at the local GP surgery, or a walk in the nearby green space.
21:00Unwinding and planningTaking stock of the day at home, reading the local news and preparing for tomorrow's deadlines at work.
What the listings and the agents leave out in London
These frequent omissions lead far too often to painful disappointments that only register after several months of living there.
The London property market is defined by fierce competition, which sometimes pushes people to gloss over significant structural or environmental flaws. Marketing photographs use flattering wide-angle lenses and artificial lighting that hide how small the rooms really are, or how little natural light there is. Behind an appealing Victorian facade there are frequently complex technical problems tied to the age of British housing stock. So it is essential to dig beyond a courtesy viewing and ask about the physical and regulatory issues that are invisible at first glance.
The true state of old water and plumbing systems
Many houses still have lead or corroded cast iron pipework that causes chronic leaks and needs heavy replacement entirely at your own cost. Replacing the risers and the waste pipes in full is a substantial works budget that never gets factored into the opening offer.
The effect of local traffic schemes and low emission zones
The introduction of low traffic neighbourhoods and the extension of environmental charging zones change car journey times, and resale value, dramatically. A property that seems quiet can end up congested by traffic displaced onto the adjacent roads that were left unprotected.
Real thermal performance and the EPC (Energy Performance Certificate) rating
Homes rated E, F or G on the British energy scale bring astronomical heating bills through the hard winter months. Bringing a leaky house up to standard, to meet future legal requirements, demands major investment in external insulation and double glazing.
Planning and construction proposals immediately nearby
Planning permission granted later for tall buildings next door can destroy your direct sunlight and your visual privacy for good. Combing carefully through the local planning register at the council offices is essential before you sign up to anything firm.
The classic traps and buying mistakes you only discover six months in
These risks underline that buying property in London is absolutely not right for every buyer.
Looked likeAn exceptional opportunity, because the asking price sat slightly below the local market.
Turned outA property with major hidden structural defects, such as subsidence or rising damp, that a quick viewing did not pick up.
Would have caught itInsisting every time on a thorough survey (a full building survey) carried out by an independent professional before any irreversible decision.
Looked likeA neighbourhood in full gentrification, with the promise of rapid and guaranteed capital growth.
Turned outAn isolated area with a persistent shortage of good schools and of local shops that last, which made daily life difficult.
Would have caught itVisiting the area at different times on weekdays and at the weekend, and reading the official crime figures along with the school performance data.
Looked likeAn older house full of authentic charm, with period floorboards and decorative fireplaces.
Turned outA permanent money pit in heating costs and in maintaining uninsulated timber joinery governed by conservation area rules.
Would have caught itBudgeting a specific allowance, right from the offer stage, for energy improvement works and electrical upgrades.
Looked likeA quick purchase thanks to the absence of a chain (a chain-free property).
Turned outExtreme administrative delays on the solicitors' side and hold-ups in verifying title, which stretched the uncertainty out over months.
Would have caught itInstructing a specialist solicitor with a reputation for responsiveness, and setting strict contractual milestones with penalties for unjustified delay.
Which buyers should absolutely hold off on investing in London for now
Having taken the time to weigh all of these factors, it is time to settle your final decision with your eyes open.
The London property market demands financial solidity that will hold under any strain, and a long-term view that some life plans simply do not allow. Committing to buy a house in the British capital without the necessary guarantees exposes the buyer to short-term depreciation or to a rapid budget squeeze. Identifying these situations of mismatch is what saves people from dramatic financial failures and points them towards more flexible rental alternatives.
The first-time buyer with no savings left once the deposit is paid
→To buy at the absolute limit of what they can borrow, keeping no cushion for the unexpected.
The slightest boiler failure, roof bill or sudden rise in mortgage rates will tip them straight into default.
The mobile professional whose international career means moving every two years
→To buy a house quickly in order to settle in, without allowing for the costs of selling again and the transaction taxes.
The high transaction costs on both the purchase and the resale in London swallow the whole of any potential gain over a period shorter than five to seven years.
The household with no tolerance for urban noise and the logistics of a huge city
→To buy in a dense district while hoping to find the absolute quiet of a rural or semi-rural area.
The capital's constant activity, the density of the traffic and the closeness of city living will generate chronic stress that is incompatible with the calm they are looking for.
The investor after an immediate, high rental yield with no management effort
→To buy a family house to let out without knowing how complex UK residential tenancy law is.
Strict taxation of rental income and regulation that protects tenants cut the expected net return drastically.
So are you genuinely ready to go ahead with buying in London?
At the end of this analysis, buying a house in London shows itself for what it is: a heavy financial commitment that tolerates no strategic vagueness. This is not a decision to be made on a sentimental impulse in front of a charming Victorian facade or a tempting listing on a property portal. It demands a perfect fit between your time horizon, your real financial strength and your capacity to absorb the structural constraints of the British market.
If you have the emergency savings you need, the professional visibility over several years and a proven tolerance for the administrative complexities of the ownership system, then you have the fundamentals to succeed. If not, renting remains a perfectly rational option that preserves your flexibility and your capital against the swings of a market in constant change.
Related questions
How much Stamp Duty Land Tax should I expect on a house in London?
Stamp Duty Land Tax is worked out on a progressive band scale, and the rates depend on the purchase price of the property and on whether you are a resident or a first-time buyer. It is strongly advised to use the official UK government calculators and to confirm the exact figure with your solicitor before you submit a firm offer.
Is a home survey compulsory before buying?
UK law does not formally require a technical inspection before purchase, but skipping that step is one of the riskiest things a buyer can do. A Level 2 or Level 3 report brings to light major hidden defects such as damp, a worn-out roof or structural problems that are invisible during viewings.
How long does a property transaction in London usually take?
The full conveyancing process, from the seller accepting your offer to the handover of the keys (completion), generally takes between three and six months. That timescale varies considerably with the complexity of the chain, how responsive the solicitors are, and how quickly the local authority searches come back.
What is the fundamental difference between freehold and leasehold in London?
Freehold means you own both the building and the land it stands on, with no time limit. Leasehold, by contrast, grants you the right to occupy the property for a fixed period set by a contract with the owner of the land, and it comes with service charges and ground rent to pay.
How is council tax calculated for a London house?
Council tax is a local charge collected by each borough to fund local public services, and it depends directly on the property's assessed value as at 1 April 1991. Properties are placed in valuation bands running from A to H, and the band determines the exact annual amount due from the household living there.
Which districts are most sought after for buying a family house?
Families generally favour the outer residential boroughs or the areas with excellent state schools and extensive green space, such as Richmond, Ealing, Wandsworth or Bromley. The choice comes down to your available budget and to how quickly you need to reach the business core of the City or the West End.
Should I budget for energy improvements on an older house?
The great majority of older London houses have energy performance that could be improved, largely because solid walls were built without modern insulation. It is strongly recommended that you build a dedicated allowance for EPC improvement works into your initial financing plan, so that you keep future heating bills under control.
What exactly does the solicitor do during a purchase?
The solicitor or conveyancer is the essential legal professional who orchestrates every legal check, drafts the sale contracts, handles the secure transfer of funds, and makes sure there are no easements or restrictive planning proposals affecting the property you have set your heart on.
Can you negotiate the asking price of a house in London?
Negotiation is a built-in part of the transactional culture in the UK property market, although how much room you have depends on how competitive the moment is and on how urgently the seller needs to move. An offer argued from the findings of the survey, or from recent sale prices of comparable properties on the same street, is a formidable lever.
What are the criteria for first-time buyer tax relief?
First-time buyers can claim substantial relief or reductions on Stamp Duty Land Tax, provided they have never owned a property before, either in the UK or abroad. The purchase price must also stay below the regulatory ceiling set by the UK tax authorities.