Putting a value on a house in the British capital means working with legal and financial conventions that sit some way from continental habits. This guide works methodically through what actually drives a London figure, so you can read an estimate, test it and understand where it came from.
Get the app
What nobody tells you.
Real prices, hidden costs and the traps to check before you commit.
What really sits behind the value of a London house
Scroll
What really sits behind the value of a London house
Putting a value on a house in the British capital means working with legal and financial conventions that sit some way from continental habits. This guide works methodically through what actually drives a London figure, so you can read an estimate, test it and understand where it came from.
Written by the ting.ad editorial team ·
East Street, London in Street View: drag to look around.
Understanding these structural trade-offs lets you approach the question of location with the detachment it needs.
A house in the British capital carries a value shaped by far more than its floor area, and the same feature can push the figure in either direction depending on condition. Behind the picture-postcard image of Victorian facades sit technical and financial realities every owner should examine methodically. Valuing well is not about finding a number you like; it is about weighing the appeal of an older building against what it costs to keep.
The architectural character of a Georgian, Victorian or Edwardian period housevsThe difficulty and cost of bringing it up to modern energy standards
Historic houses carry a cachet nothing replicates, but they demand a serious budget for insulation, heating replacement and the upkeep of listed features, and a valuer will net that work off the figure.
A private garden or planted outdoor spacevsThe regular maintenance the island climate and urban pollution demand
Owning a piece of ground in London is a rare luxury and reads clearly in the plot adjustment, but it carries a constant upkeep burden or the cost of bringing in specialists.
Complete freedom to alter the property, with no shared building to answer tovsFull financial responsibility when structural work or a roof replacement falls due
Unlike an apartment, no collective reserve fund spreads the major structural risk on your roof or foundations, so condition carries the whole weight in the estimate.
A solid property asset at the heart of a global cityvsLiquidity that is sometimes thinner than for mid-sized apartments
Well-located houses hold their value remarkably well, but a more selective market means fewer recent comparable sales to anchor a figure against.
Why are you valuing this London house?
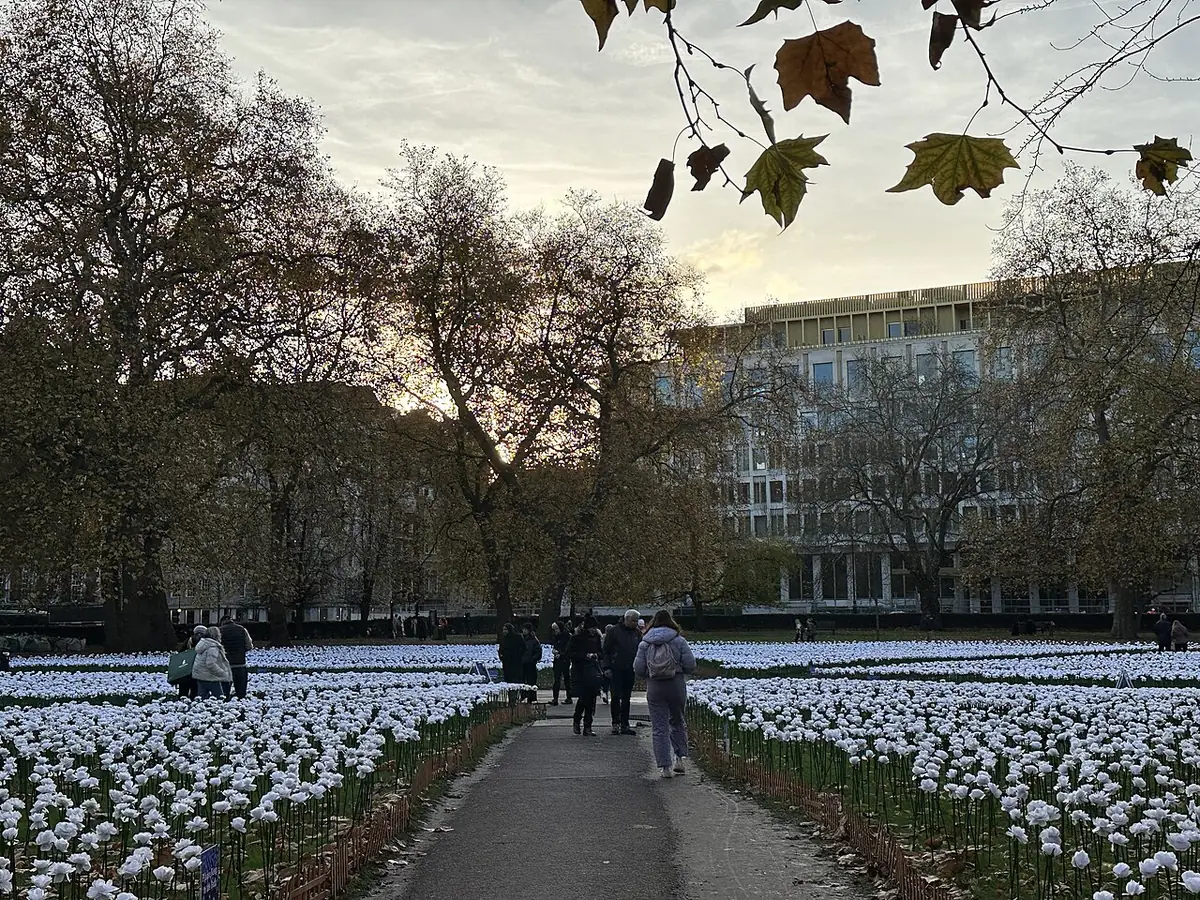
Green squares offer a quiet break from city life — Photo: Matt Brown · CC BY 2.0 · Wikimedia Commons
With your own position clear, it is worth measuring precisely what separates British valuation practice from the reference points you are used to.
What a valuation needs to tell you depends less on the raw floor area than on the decision the figure has to support. Whether you are testing the market before a sale, refinancing, or holding for the long term, the reason you are asking changes which evidence matters and how much precision you need. Being honest about the purpose is what keeps an estimate from being quietly misused.
Valuing an inner suburban house on transport strength
You care about proximity to the business districts alongside the calm of a residential street, and that pairing is exactly what drives the figure in zone 2. Expect the valuation to reward the fast Underground connection and the amenities within walking distance, while discounting the smaller floor area or shorter garden that comes with the location. Ask any valuer to show you which of those two factors is carrying the number.
Reading the premium attached to sought-after school areas
Where the quality of state or private schools and the safety of nearby green space is the draw, the catchment premium is real and it is one of the least visible parts of a figure. Quieter districts value strongly on those grounds even where the commute is longer. Ask for comparable sales inside the same catchment rather than the same postcode, because the boundary can move the number more than the street does.
Valuing the upside as well as the property as it stands
Here you want two figures: what the house is worth today, and what a loft conversion, a rear extension or a home office would add net of its cost. Look at how the surrounding area is moving, the infrastructure projects due to land, and the strength of underlying demand, then have the uplift priced against completed local examples rather than assumed.
Valuing from abroad: what genuinely works differently
With those institutional reference points in place, the question of exactly where in the capital the house sits becomes the decisive one.
Arriving from another property culture to value a London house exposes you to legal and contractual conventions that can be genuinely disorienting. From the ownership system to the roles played by estate agents, surveyors and solicitors, the process rests on mechanisms of its own. Anticipating those differences is what keeps a figure defensible rather than merely optimistic.
From abroad
A single, absolute and permanent form of ownership over land and building alike
London
The distinction between freehold and leasehold, depending on the nature of the property
Check the number of years left on the lease if the house is leasehold, because it feeds directly into the value and into what a lender will advance against it.
From abroad
A deed of sale drawn up and secured by a single public officer
London
Independent solicitors acting for each side, and sold prices published afterwards by HM Land Registry
Recorded sold prices, not asking prices, are the evidence a valuation should rest on, so ask which completed transactions a figure was drawn from.
From abroad
A centralised, standardised statutory technical inspection
London
Independent structural surveys commissioned by the buyer (HomeBuyer Report or Building Survey)
You have to appoint your own surveyor to establish the true state of the roof structure, plumbing and insulation, because those findings are what justify a condition adjustment on the figure.
From abroad
Local taxes pegged to a historic cadastral value
London
Annual Council Tax set by the assessment band your property falls into
That amount varies significantly from one borough to another and sits on top of running costs, but the band reflects a 1991 assessment and is no guide to the property's value today.
How London districts value differently, and why
Once the geography is clear, an objective look at the price structure and the associated costs becomes essential.
The London market splits into micro-markets with sharply drawn identities, each with its own price behaviour, community life and transport pattern. Reading a valuation is less about distance from the centre than about the daily feel of a street, the green space nearby and how well it connects. Mapping those expectations carefully is what tells you whether a comparable is genuinely comparable.
The northern boroughs and their historic parks
A village atmosphere built around farmers' markets, independent cafes and large stretches of green space.
Suits
Families wanting a leafy setting without cutting themselves off from the cultural life of the city.
Trade-off
Some of the highest values per square metre in the capital, and strong competition for the scarce family houses that set the comparables.
The eastern districts still in transition
Creative energy and an architectural mix of converted docks and modernised Victorian houses.
Suits
People working in tech or alternative finance who want somewhere connected and current.
Trade-off
An unfinished urban transition on some streets and intermittent construction noise, which makes figures move street by street.
The residential west and south-west
Genuinely quiet tree-lined avenues, the Thames close at hand and well-regarded schools.
Suits
Those who put residential calm, safety and direct access to large parks first.
Trade-off
Relative distance from the central arteries and a very demanding overall cost of entry.
What London house figures actually look like
With the financial picture in hand, you can turn calmly to the legal question of what exactly is being valued.
Valuing a house in London is not a matter of multiplying a headline rate per square metre by a floor area. The figure has to sit alongside the transaction costs a buyer will face, notably Stamp Duty Land Tax, and the recurring upkeep an older building demands. Holding the full financial picture in view is what stops an estimate from falling apart the moment a lender or a surveyor looks at it.
londonFor saleHouseestimate
Median price / m²£6,232Half the apartments sell below this
Median price£781kthe average is 14% higher — a few very large properties pull it up
Most common2 bedrooms63 % of listings
Average size119 m²
By number of bedrooms
Bedrooms
Share of market
Avg price
Price / m²
Avg size
2most common
63 %
£796k
£6,691
119 m²
3
28 %
£971k
£6,166 −6 %
158 m²
4
9 %
£1.18m
£6,035best value / m²
196 m²
Each row is an average, compared against the area average of £6,560 / m². These are indicative estimates of a typical local market, not a measured sample of live listings. Check current listings before relying on them.
What is actually being valued: freehold versus leasehold
With the legal form clarified, it is worth looking at how a figure is arrived at, step by step.
The legal structure of ownership in the United Kingdom carries subtleties that change the nature of what you hold, and therefore what it is worth. Understanding the line between outright ownership of the land and a time-limited right of occupation is essential for any owner coming from elsewhere. That distinction shapes not only what you are free to alter, but how the value behaves over time.
Outright ownership (Freehold)
You own both the building and the land it stands on, with no time limit and no ground rent payable to anyone else. That regime gives complete freedom over management, extension and renovation, which is why it is the usual basis on which a London house is valued.
What it changesYou alone decide on maintenance work and carry the costs directly, with no third-party landowner in the picture, so condition and plot are the two levers that move your figure.
A time-limited right of use (Leasehold)
More common for apartments but found on some houses, this regime grants a right of occupation for a term set by an original lease that is often long. You pay ground rent and contribute to shared costs managed by the owner of the land (the freeholder).
What it changesWatch the number of years left on the lease closely, because a term under 80 years makes lending markedly harder to obtain and depresses the value of the property.
The rule to understand before you trust a figure on your house
All of these steps fit into a precise sequence run by the professionals around you.
Valuation in Britain follows a strict chronology in which a figure hardens only gradually, and the parties are not committed until contracts are exchanged. An agent's appraisal, an automated estimate and a lender's mortgage valuation are three different numbers produced for three different purposes, and only the last of them has money behind it. Grasping that sequence protects an owner from mistaking an opening figure for a settled one.
An estate agent gives an appraisal figure and an offer follows, accepted subject to contract, with no binding legal weight at that stage.
The solicitors appointed by both sides carry out the land searches and examine title, confirming what is actually being sold.
The independent surveyor appointed by the buyer reports in detail on the structural and damp condition of the house, which is where condition adjustments come from.
The lender runs its own mortgage valuation and the borrowing is confirmed, which is the moment an institution puts its own number on the property.
The parties agree the final contract terms and fix the date on which ownership transfers.
Exchange of Contracts takes place: the price becomes irrevocable, a non-refundable deposit is paid, and the figure is on its way to being recorded as a sold price.
How a London house gets valued, step by step
Valuing a house in London draws on a network of specialists whose work has to be sequenced properly if the figure is to hold up. From the first appraisal through to the sold price being recorded, each party plays a defined role. Following a structured order is what keeps an estimate steady when the paperwork throws up surprises.
The ownerGathering the paperwork: title, EPC, Council Tax band, guarantees and any work carried outThis first step is what lets a valuer work from evidence rather than assumption, and it is worth doing before anyone visits.
The estate agentMarket appraisal and a suggested asking figureThe agent works from recent local sales and current competition, so ask which comparables the suggested figure rests on.
The solicitorTitle checks and HM Land Registry sold price evidenceThey confirm there are no hidden easements, check local planning records and establish exactly what is being valued.
The independent surveyorDetailed structural inspection of the building (Building Survey)They uncover hidden structural defects, damp problems or work needed to meet current standards, each of which adjusts the figure.
The lender's valuerMortgage valuation carried out for the bank rather than for youThis figure answers a different question, namely what the property is worth as security, and it can come in below the agreed price.
The owner and their advisersReconciling the figures and settling on a defensible numberWhere the appraisal, the survey and the lender's valuation disagree, the gap between them is usually condition, lease term or plot.
House or apartment in London: why the two value on different logics
With that distinction understood, the question of the wider budget and the recurring costs presses on every owner.
Valuing property in London means recognising at the outset that a traditional Victorian or Edwardian house and a modern apartment, whether in a new development or a conversion, are assessed on genuinely different logics. The difference is not a matter of taste or headline budget: it runs through the daily experience of the building, the maintenance obligations attached to it and the way the value behaves over the long term in a city where space keeps getting scarcer. Houses generally come with their own access to the outside, a garden and complete independence from neighbourhood decision-making, which is what families in search of stability and secure space are paying for. That independence carries a considerable financial and practical cost, however, because roof, facade and foundation maintenance falls entirely on the owner with no possibility of sharing it with anyone else, and a valuer will read the state of all three straight off the survey.
A London apartment, whether tucked into a handsome converted townhouse or set in a contemporary tower with a concierge, offers formidable flexibility and service charges that are often offset by shared facilities such as a gym, security or a lift. Living in one means accepting communal life and the strict regulatory framework of leasehold, where management of the building sits with a freeholder or a managing agent. Service charges can prove unpredictable and rise substantially from one year to the next, weighing heavily on the household budget well beyond the monthly mortgage payment, and a rising charge visibly depresses what buyers will offer.
On liquidity and resale, small apartments well served by public transport, particularly along the Jubilee line or the Elizabeth Line, find buyers faster among a young and mobile professional population, which keeps their comparable evidence plentiful and their figures tight. Single-family houses, rarer in central areas such as Kensington, Islington or Hackney, have historically shown remarkable resistance to downturns, because the supply of freehold there is structurally limited by the shape of the city. The trade-off in a valuation is therefore between the immediate comfort of a private garden and the administrative constraints of leasehold, alongside your capacity to absorb the unexpected costs that come with older London building stock.
Finally, the time horizon matters, because it changes what a figure is actually for. If you expect to sell in the medium term, high transaction costs and the legal complexity of leases can erode the net gain, which makes a central apartment the more agile asset. If you are anchoring a family for ten or fifteen years, a house, even one needing significant energy renovation work, offers a quality of life nothing matches and a solid store of value against British property inflation.
The costs a London house figure has to sit alongside
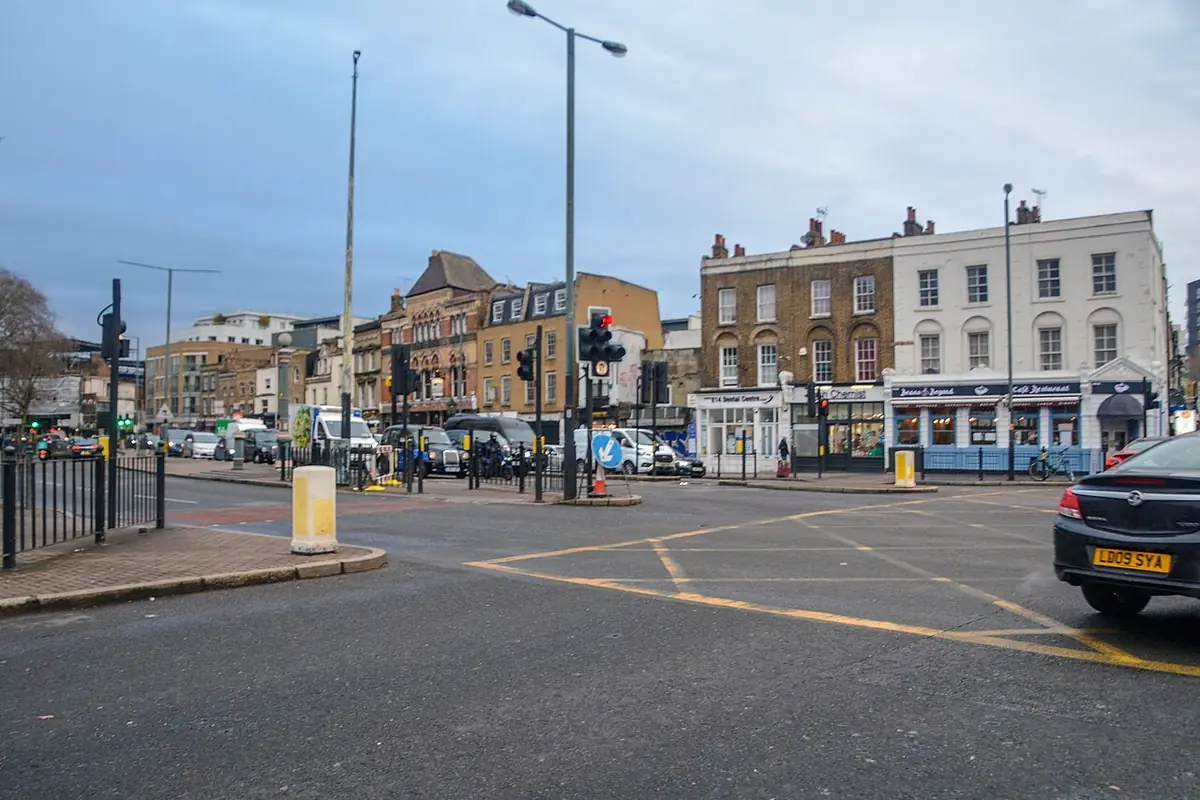
Terraced houses and corner shops along a typical London street — Photo: Lewis Clarke · CC BY-SA 2.0 · Wikimedia Commons
To see how this budget plays out day to day, it helps to look at an ordinary day in the capital.
A London house valuation cannot stop at the figure advertised on the property portals, because a range of additional charges and specific taxes sit between that number and what a transaction actually costs. Progressive transfer duty, Stamp Duty Land Tax, joins the legal fees and the survey costs needed to keep hidden defects from surfacing later. Beyond the transaction, the cost of running a house in London, marked by Council Tax bands and the energy consumption of older buildings, shapes what buyers are prepared to pay and therefore what the property is worth.
Transaction costs and taxes attached to a London house at the value it is assessed at
Cost item
Order of magnitude or rate
Effect on the overall budget
Stamp Duty Land Tax (SDLT)
Progressive scale from 0% to 12% (2% surcharge for non-residents)
Runs to several tens of thousands of pounds depending on the value of the property
Solicitor's fees (conveyancing)
Between GBP 1,500 and GBP 3,500 excluding tax
Varies with the legal complexity of the title and the searches
Survey report (Level 2 or 3)
Between GBP 600 and GBP 1,500
Essential for identifying damp and roof problems that adjust the figure
Mortgage broker fees
Between GBP 500 and 1% of the amount borrowed
Opens access to negotiated rates with British banks
Stamp Duty rates are revised regularly by the British government and depend on your tax residence status.
Annual running costs and recurring charges
Type of cost
Estimated annual amount
What makes it vary
Council Tax (local property charge)
Between GBP 1,200 and GBP 3,500 depending on the borough and the band (A to H)
Central and sought-after districts carry the highest contributions
Home insurance (buildings and contents)
Between GBP 400 and GBP 900 a year
Depends on floor area, location and claims history
Energy bills (gas and electricity)
Between GBP 1,800 and GBP 3,500 depending on insulation
Uninsulated Victorian houses demand a very high heating budget
Routine maintenance and a reserve for works
1% to 2% of the value of the property a year
Covers roof, plumbing and facade repairs as they fall due
Energy costs have been highly volatile, which makes the EPC rating critical both to your budget and to what buyers will offer.
An ordinary Tuesday for a London owner, and what it tells a valuer
Beyond this well-worn routine, plenty of things never appear in the marketing material and deserve close attention.
Living in a London house means organising around the distance between the residential areas and the main employment centres. An ordinary Tuesday shows the reality of it, between the commute, neighbourhood life and the running of the house itself. Walking through the day is a practical way to see which everyday facts, commute times, school access, local services and the state of the building, end up carrying weight in a valuation.
07:30A residential district (Ealing or Dulwich, for example)Waking up and getting ready in a Victorian house. A quick check of the temperatures and the boiler pressure, a routine worth keeping records of, because heating and insulation are among the first things a surveyor asks about.
08:15The local school or nurseryWalking the children to a school rated Outstanding by Ofsted, a factor that weighed heavily when the house was chosen and that carries a measurable catchment premium in the figure.
08:45The Underground station or National Rail stationBoarding the train or Underground line for the City or Canary Wharf, on a frequent and modern network. Door-to-door commute time is one of the clearest dividing lines between comparable streets.
12:30The central London business districtA quick lunch break in the centre, combining work meetings with chasing a plumbing quote for the house remotely, the kind of documented work that supports a condition adjustment later.
17:30The local high streetLast-minute shopping with the independent traders nearby (butcher, greengrocer), the neighbourhood life that keeps demand steady on a street before heading home.
19:00The garden and the inside of the houseFamily time in the living room, a quick look over the garden and sorting the administrative post, including the utility bills and the Council Tax notice that any valuation paperwork will ask for.
What agents, listings and automated estimates never tell you about a London house
These blind spots explain why some owners look back six months later with real regret.
London property listings are photographed with considerable ingenuity to flatter volume and light, often at the expense of the technical and environmental reality of the building. Behind a freshly repainted Victorian facade there are sometimes heavy structural problems that nobody volunteers, and that an automated estimate cannot see at all. Identifying these blind spots before you accept a figure is what prevents an expensive correction later.
The true state of the shared walls and the Party Wall Act
In London terraced and semi-detached houses, load-bearing walls shared with neighbours are tightly regulated. Any extension or structural alteration requires a formal and costly party wall procedure that can hold work up for months, which is why extension potential should never be priced into a figure until it has been checked.
Noise that is inaudible on the day of a viewing
A street that is quiet on a Saturday afternoon can turn out to be a major bus or lorry route at weekday peak times. The sound insulation of old sash windows is often inadequate against continuous urban traffic, and buyers who discover it late reduce their offers accordingly.
Real energy performance and heat loss
Many older houses carry mediocre EPC ratings (D or E), which translates into punishing gas bills in winter and a raised risk of condensation and mould. A whole-house thermal retrofit is often an investment of more than GBP 20,000, and that figure is deducted from what a buyer will offer.
Planning and construction projects nearby
Planning permission granted for a neighbouring building or an extension on the adjoining plot can destroy your direct sunlight and depress the value of your property. Checking the local borough planning register carefully is an absolute precondition to trusting any figure.
The valuation mistakes London owners only spot six months later
Given these demands, it is fair to ask whether a figure of this kind is one you should be acting on at all.
Looked likeAn appealing figure in a rapidly gentrifying district, with immediate upside assumed
Turned outAn area cut off from the fast transport network, producing exhausting daily commutes and a difficult resale if the market turns
Would have caught itChecking the real door-to-door journey time at peak hours and testing the route at different times of day before accepting that any premium is justified.
Looked likeA period house full of character, with original floorboards and fireplaces
Turned outA thermal sieve needing the heating system replaced outright and the ageing electrics brought fully up to standard
Would have caught itCommissioning an independent RICS Home Survey Level 3 and netting a costed schedule of works off the figure rather than admiring the features.
Looked likeA reassuring figure with no urgent work apparent during quick viewings
Turned outPersistent damp in the semi-basement walls (basement or ground floor), hidden by a fresh coat of paint before the property went on the market
Would have caught itInsisting on written assurances about dry rot and rising damp, and having any cellar inspected by a damp-proofing specialist before the number is settled.
Looked likeMinimal local charges and a peaceful district run by the local authority
Turned outA sharp rise in Council Tax and Low Traffic Neighbourhood (LTN) restrictions lengthening journeys by car
Would have caught itReading the borough's voting record and road scheme plans, and asking immediate neighbours what daily life on the street is actually like.
Who should not act on a London house valuation right now?
With all of this set out clearly, it is time to decide what to do with the number in front of you.
A favourable valuation on a London house is often treated as a signal to act, but for several household profiles it is a poor basis for a decision. The rigidity of the British market, combined with high transaction costs and moving interest rates, demands a personal and financial position that is genuinely stable. If you recognise yourself in one of the profiles below, the figure is information to hold rather than a reason to move.
The professional on a short assignment or with uncertain international mobility
→Continuing to rent something flexible rather than acting on the estimate
Stamp Duty Land Tax and the agency commission on resale absorb the entire potential gain if the property changes hands again inside five to seven years, whatever the valuation says.
The household whose deposit is only just sufficient, with no emergency savings
→Waiting and building the savings before committing on the strength of a figure
Running an older London house inevitably generates unforeseen repair costs (roof, boiler, plumbing) that need cash available immediately, and no valuation makes provision for them.
The owner with no appetite for administration or renovation work
→Looking at newer leasehold stock, or staying where they are
London housing stock is overwhelmingly old, and the value in it is unlocked by a considerable personal investment of time and site management with local trades.
So how much confidence should you place in your London figure?
Putting a value on a house in London is more consequential than it first appears, because the number ends up steering decisions well beyond the purely financial. Doing it properly demands clear sight of the constraints of the British market, the complexity of transactions and the realities of maintaining older building stock. If you have accounted for the full range of associated costs, from the local charge to the energy bills, and your horizon runs well beyond five years, then the fundamentals of London property work in your favour.
A figure you can rely on rests above all on the rigour of the preparation behind it: never let a tense market rush you, favour locations with durable transport infrastructure, and surround yourself with independent professionals who work carefully. Trade-offs are part of owning property in a global city, but they should be chosen deliberately rather than discovered through a technical or legal surprise after the fact.
Take the time to see the property at different points in the day, to work through the survey reports line by line, and to test any figure against accredited local advice. Your London house should be somewhere to live and a solid anchor, not a permanent source of stress rooted in an underestimated budget or work nobody costed. It is now for you to weigh the evidence and turn the number in front of you into a decision you can defend.
Related questions
How long does a London sale take to complete once a value has been agreed?
Conveyancing generally runs three to five months between the offer being accepted and completion. The delay comes from the legal searches the solicitors carry out and from the checks on title. Until completion, the agreed figure is a working number, not a recorded sale price.
How does the difference between freehold and leasehold affect a London house valuation?
Freehold means you own both the building and the land it stands on, which is the case for most houses, and it values cleanly. Leasehold, more common for apartments, grants a right of occupation for a fixed term with ground rent and service charges payable to the owner of the land, and the remaining term feeds directly into the figure.
What legal costs sit alongside a London house transaction?
The United Kingdom has no notary in the continental sense; solicitors handle the legal side. The main acquisition tax is Stamp Duty Land Tax (SDLT), charged on a progressive scale that depends on the value of the property and on your tax residence status, so it moves in step with the valuation itself.
Do you need a survey to understand what a house is worth?
Commissioning a RICS Home Survey Level 2 or 3 is strongly advised, because it identifies hidden defects, damp problems and roof or structural work that will need bringing up to standard. That is particularly true of older Victorian houses, where the survey findings translate straight into a condition adjustment on the figure.
How is Council Tax worked out for a London house, and does it track the valuation?
Council Tax is a local charge collected by the borough to fund nearby public services. The amount depends on the assessed value of the property on 1 April 1991, sorted into eight bands running from A (the cheapest) to H (the highest), which is why the band tells you almost nothing about what the house is worth today.
Does buyer status change what a house is worth in London?
Yes, non-resident investors can buy property in London, but they pay a 2% surcharge on Stamp Duty Land Tax and face stricter lending criteria from British banks. That extra cost sits between the asking figure and what a buyer is willing to commit.
What is the Party Wall Act, and why does it come up in a valuation?
The Party Wall Act is British legislation governing work that affects walls shared with your neighbours. It requires a formal notification procedure and a written agreement drawn up with the help of surveyors before structural renovation begins, which is why any extension potential you are counting on has to be checked before it is priced in.
What effect does the EPC rating have on the value of a house?
The Energy Performance Certificate (EPC) measures the energy efficiency of a home from A to G. A poor rating signals high heating bills and can weigh on resale value as buyers grow steadily more sensitive to running costs.
How do interest rates move London valuations?
Bank of England base rates dictate the cost of mortgages. High rates reduce how much households can borrow, which puts downward pressure on advertised prices or slows the volume of transactions on the market, thinning out the comparable evidence a valuation rests on.
Which London districts hold their value best for houses?
Sought-after residential areas include well-connected districts such as Islington, Hackney, Wandsworth and Ealing, which combine family living, good green space and quick access to the central London employment centres.